Financial Literacy and Money Management: Real-World Training for Young Adults with Special Needs
Your money skills can grow through practice, even if information needs to be presented in a different way. With clear teaching and support that respects your choices, everyday decisions can become easier to manage.
A financial advocacy service provides practical support to help you understand and manage your finances while building independence. This article offers general UK guidance, not a benefits decision or legal advice.
Key Takeaways
- Start with what you already know about money.
- Practise with everyday choices and real purchases.
- Use support that fits your needs and respects your decisions.
- Check benefit rules and specialist help when you need them.
People have a range of ways to learn, and a person with a learning disability may benefit from clear, repeated practice. A person with learning difficulties may also need information presented accessibly, though the terms are not interchangeable. Begin with what you can already do confidently.
How can money management support learning difficulties in everyday life?
Check whether you can recognise coins and notes before asking you to work out a shopping budget. Start with recognition, then practise one choice at a time; your starting point is what you can already do, not an assumed level of ability.
Check which coins and notes you recognise before introducing calculations or a shopping budget.
Talk about income as money you receive, such as wages or benefits. If a family member transfers part of your DLA or PIP into their own account, agree what that money is expected to cover. Discuss needs, such as lunch or travel, alongside wants, such as a treat, using an actual purchase.
Start from what the young adult already understands
People learning to handle money may recognise some coins but find note values harder to tell apart. Ask what feels familiar, and give time to answer without turning it into a test. Then use a small, real amount to practise choosing what to buy and checking whether the price fits.
Explain that a lower price can leave more money for another need, while a familiar brand may still be worth choosing if you prefer it. Four 70p chocolate bars each week cost about £145 over a year. A four-pack of slightly smaller bars at £1 a week costs £52.
Worksheets for money skills for adults with learning disabilities in the UK
You can make simple practice sheets at home or with a trusted supporter. One exercise could ask you to match pictures of coins and notes to their values. Another could show two prices and ask which costs less, while a final exercise records an item, its price and the money paid.
Keep each task short, with large print and clear pictures if these help. The phrase money skills for adults with learning disabilities worksheets in the UK describes the kind of activity to look for or create; it does not guarantee that a particular worksheet download exists. The US-based FDIC Money Smart for Adults curriculum includes exercises on spending, saving, banking and debt, though its US banking guidance may not fit the UK.
Help young people with learning disabilities understand money through everyday practice
Helping young people with learning disabilities to understand money can begin with a shopping list and a meal plan. Compare brands together, then discuss the pros and cons aloud: price, size and whether you like the product. A short money diary can help you record what came in and what you spent.
Let the young adult make the choice where possible, including choosing a preferred brand even when another costs less. These activities give people learning opportunities without taking control away. Confidence grows through repeated, real purchases, which can lead naturally to a simple system for keeping money and bills organised.
How can a simple budget protect day-to-day spending?
A budget makes it easier to see whether essential costs are covered before you choose what else to spend. It lists the money you receive and the things you spend money on each month. Make the amounts visible, so money for essentials stays clear before optional spending begins.
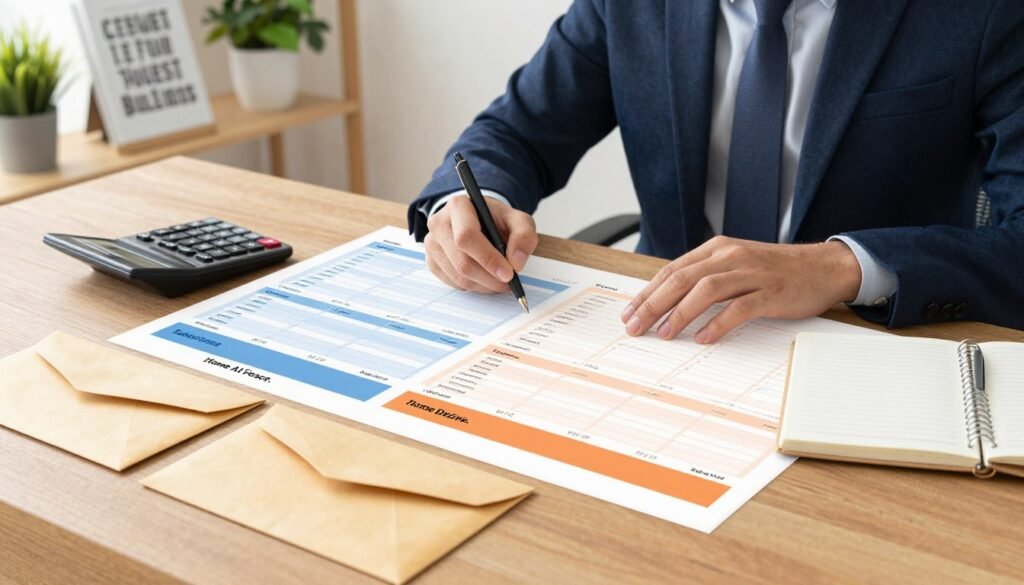
Build a visual, realistic weekly budget
Write down income and costs in plain language, then sort costs into essentials and optional spending. Essentials might include food, travel and regular bills. Optional spending might include a café visit or a game. Check what is left after essentials, and make the weekly amount realistic for your routine.
Labelled envelopes can hold set amounts for different costs. Separate digital pots in a bank account can do something similar, if those features suit you. Money management for adults with learning disabilities can use pictures, colour or simple numbers, depending on what makes your finances easiest to understand.
Make banking and borrowing safer
Compare suitable bank accounts for adults with learning disabilities in the UK with a trusted supporter. Banks have accounts for vulnerable customers who need more support to manage money. Check that account access and controls fit your wishes, and consider reminders or Direct Debits for regular bills where appropriate.
Credit and loans cost more over time because interest is added. Before borrowing, check the total repayment: a £100 loan with £20 interest means paying back £120. A study comparing 39 adults with ADHD and 83 without ADHD found lower scores for understanding financial information in the ADHD group; results describe group differences, not every person. Read the study of financial judgement in adults with ADHD.
Lost cards, scams, impulse spending or lending money to an unreliable friend can happen to anyone. Contact your bank promptly if a card is lost or you spot a suspicious payment. Agree a prevention plan without blame, such as changing card settings or deciding together how to respond to requests for money.
If bills, benefits or financial decisions still feel hard to manage, suitable specialist and independent support can help you find the next step.
Where can young adults find benefits and specialist financial support?
When a young person turns 16 or 18, their family may need to review benefits and other support. Check the individual situation, because a learning difficulty or disability diagnosis alone does not establish benefit eligibility.
Benefit entitlement depends on the person’s circumstances and the rules for each benefit, not diagnosis alone.
As disabled young people reach 16, 17, 18 or 19, they may become entitled to benefits and support in their own right. Entitlement can depend on education, job-seeking and benefit status. Parents’ or carers’ benefits and tax credits can also be affected by the young person’s circumstances. Check current rules on GOV.UK or with Citizens Advice rather than assuming a payment will be available.
Dosh provides financial advocacy for people with a learning disability, helping them manage money and build independence. For information and practical help, consider these services:
- Dosh for financial advocacy.
- Mencap for information and its Learning Disability Helpline on 0808 808 1111.
- Scope for practical money guidance.
- MoneyHelper, previously called the Money Advice Service, for budgeting and money-management guides.
- Citizens Advice for independent help with bills and debt, online, by phone or at a local office.
The Financial Conduct Authority with the National Autistic Society, and United Response, offer Easy Read banking and finance materials. The National Autistic Society also shares money-management information for autistic people. If extra communication or support from utility providers would help, ask about joining their Priority Services Register.
Support with someone else’s finances can take different forms. A third-party bank mandate gives account access or help without replacing the account holder’s decision-making rights. A DWP appointee manages welfare-benefit claims and payments when someone cannot manage those matters. A lasting power of attorney covers property and financial affairs within its authority, where that arrangement applies. A deputy makes financial decisions authorised by the Court of Protection.
| Arrangement | What it covers | When it may be considered |
|---|---|---|
| Third-party mandate | Permission for a trusted person to access or help manage a bank account | When account help is wanted without replacing the account holder’s decision-making rights |
| DWP appointee | Management of welfare-benefit claims and payments | When someone cannot manage their benefit matters |
| Lasting power of attorney | Property and financial affairs, within the document’s authority | When a person chooses someone to act for them in advance, where this arrangement applies |
| Deputyship | Financial decisions authorised by the Court of Protection | When a person lacks capacity for relevant decisions and no lasting power of attorney is in place |
Legal options and terms depend on the UK nation and the person’s circumstances, so check the right route before acting. Check eligibility and agree any support around the young adult’s own choices.
Conclusion
Financial confidence develops through supported experience, not one lesson. Small chances to make real choices can build skills, while trusted supporters help protect independence rather than take it away.
Choose one ordinary purchase this week and, if the young adult wants help, practise checking its price, paying and counting the change together. Agree the support beforehand, then let the young adult lead as much as feels comfortable.